GOLD · ~$4,135–4,180/oz “A Hot CPI Hit Gold for $100, Then Falling Yields Gave It All Back”
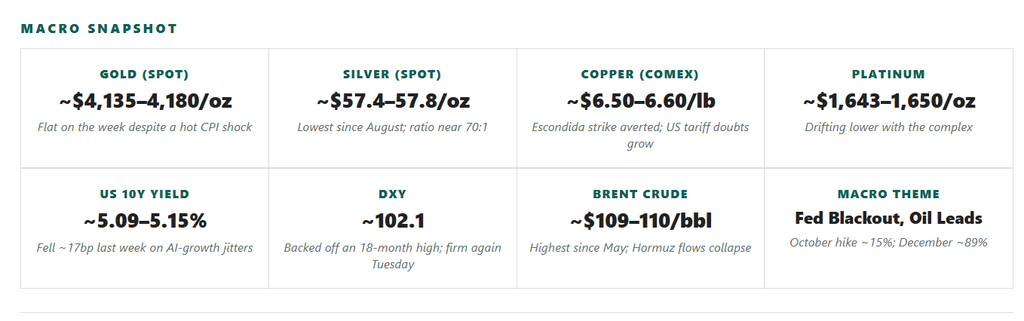
WHAT HAPPENED. Gold spent last week inside a $4,073–4,217 range and settled at $4,165.40 on Friday, October 16, down about 0.7% on the week. The low came on CPI day, when the metal dropped roughly $60 within 15 minutes of the release and bottomed near $4,074 around midday. It then recovered steadily, helped by a bond rally. Spot gold dipped to about $4,136 in early Asian trade on Tuesday, October 20 as the dollar firmed again.
WHY IT HAPPENED — PRIMARY DRIVER (INFLATION RE-ACCELERATES, BUT THE FED CAN WAIT). September CPI came in at 3.7% year-on-year against a 3.6% forecast, with gasoline up 9.1%, and core CPI rose to 2.6% from 2.4%. Producer prices then jumped 1.3% on the month, taking the annual rate to 6.3%, the highest since December 2022. October hike odds briefly spiked to about 50% after CPI. Fed Chair Kevin Warsh declined to signal an October hike in remarks in Bangkok on Friday, and odds fell back to roughly 15%, while December pricing stayed near 89%. Fed Vice Chair for Supervision Michelle Bowman said she saw no urgency to act further, while San Francisco Fed President Mary Daly said more hikes were likely but timing was open.
SECONDARY DRIVER (YIELDS FELL ON AI JITTERS; OIL KEEPS INFLATION RISK ALIVE). The 10-year Treasury yield slid about 17 basis points on the week, to roughly 5.09% from a 5.3% peak, as a tech-stock selloff tied to doubts about AI-driven growth pushed investors into bonds. That lower-yield bid is what rescued gold from its CPI low; 13 consecutive weeks of inflows into gold-backed ETFs have also supported the metal. Against that, Brent closed Monday at $109.55, after touching $110.70, its highest since May 20, which sustains the inflation expectations that keep a December hike in play.
SCENARIOS. Gold is still about 25% below its January 29 record of roughly $5,595, and has repeatedly failed above $4,200.
- Bull case: yields keep falling as the AI-growth worry builds, and gold breaks above $4,215 toward $4,300.
- Bear case: flash PMIs and Michigan inflation expectations come in hot, yields rebound and gold retests the $4,070 CPI low.
- Main catalyst: the direction of the 10-year yield in a week with no Fed speakers, no CPI and no payrolls.
SILVER · ~$57.4–57.8/oz “A 6% One-Day Drop Takes Silver to Its Lowest Since August”
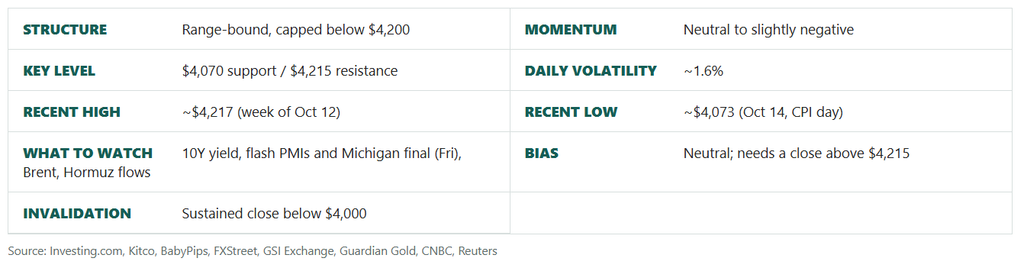
WHAT HAPPENED. Silver fell 6.16% on CPI day, touching a low near $56.90–58.50, its weakest level since August, then clawed back to roughly $57.40–57.80 by Monday, October 19. It is now about 15% below where it traded a month ago.
WHY IT HAPPENED. Silver’s higher beta to rate expectations cut hard against it on CPI day, and the bounce since has been smaller in absolute terms than the drop. The gold-silver ratio widened from about 69 to roughly 70 on the week, which fits the pattern of silver underperforming during hawkish repricings. Silver ETF holdings edged up to about 805.6 million ounces, a sign that investors are not abandoning the metal at these levels.
INDUSTRIAL DEMAND & PHYSICAL DEFICIT. The structural deficit thesis is unchanged, but near-term price action is set by yields and the dollar.
- Bull case: yields keep slipping and silver reclaims $60–61.
- Bear case: a hot data run revives hike pricing and silver breaks below $56.90 toward $55.
- Main catalyst: the 10-year yield and Friday’s flash PMIs.
COPPER · ~$6.50–6.60/lb “Labour Risk Fades, but the US Tariff Premium Is Draining Away”
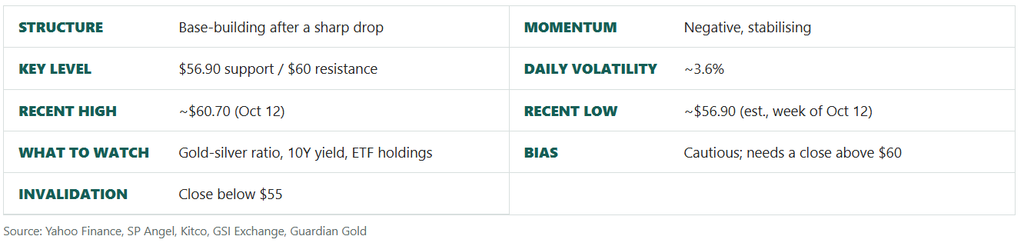
WHAT HAPPENED. COMEX copper was around $6.57/lb on Monday, October 19, about 4.6% below its September 9 record of $6.89 and up roughly 32% year-on-year, while LME copper eased to about $14,361 per tonne from $14,451. A prediction-market read put 85% odds on copper settling above $6.51 on October 23, implying a consolidation rather than a breakdown.
WHY IT HAPPENED — SUPPLY (PRIMARY DRIVER). The two labour risks flagged last week have largely cleared: Escondida’s supervisors’ union and BHP agreed a 36-month contract on October 14, and Centinela workers voted on Saturday to end their strike. The mine’s supply problem is real regardless, with BHP reporting Escondida output of 252,600 tonnes in July–September, down 19% from the previous quarter and 23% from a year earlier on lower ore grade (0.81%), maintenance, bad weather and a fatal accident on September 23. The bigger shift is on the demand-policy side: the COMEX premium over LME has collapsed in recent weeks as doubts grow that Washington will follow through on refined-copper tariffs, after a report last month that the plans had stalled on inflation concerns.
DEMAND (SECONDARY DRIVER). China’s growth beat forecasts, a supportive signal for industrial demand, and grid and AI-infrastructure demand stay intact.
- Bull case: tariff clarity returns and ex-US inventories keep tightening, pushing copper back toward the $6.89 record.
- Bear case: a formal tariff retreat removes the remaining US premium, sending copper toward $6.20–6.40.
- Main catalyst: any White House statement on the refined-copper tariff, and follow-through in Chinese demand data.
PLATINUM · ~$1,643–1,650/oz “Sliding With the Complex, Without a Deficit Story to Lean On”
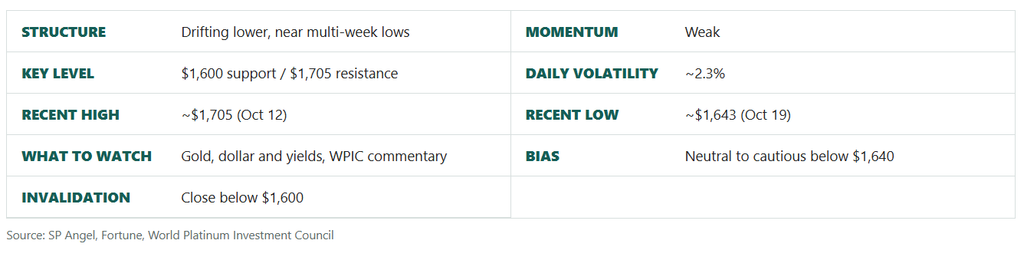
WHAT HAPPENED. Platinum traded around $1,643–1,647 on Monday, October 19, little changed from $1,644 the session before and below the $1,685–1,705 zone of the prior edition. Palladium eased to about $1,128.
SUPPLY & DEMAND BALANCE. The fundamental picture is unchanged: the WPIC projects a 265,000-ounce surplus in 2026, with automotive demand down 4% and industrial demand up 5%. Without a deficit narrative, platinum is following gold and silver’s rate-driven swings.
SCENARIOS.
- Bull case: falling yields lift the complex and platinum retakes $1,700.
- Bear case: a firmer dollar and hot data break $1,640 and open the way to $1,600.
- Main catalyst: gold direction and the 10-year yield.
This report is for informational purposes only and does not constitute investment advice. All prices are approximate and subject to market conditions. · Pan Asia Market Intelligence · 19 October 2026