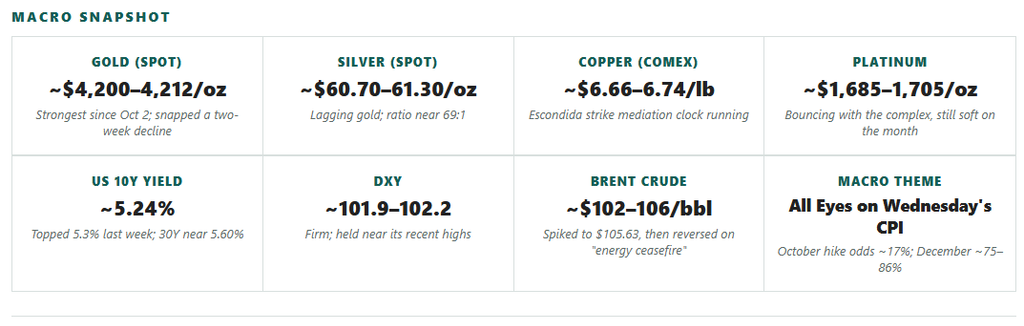
GOLD · ~$4,200–4,212/oz “A Two-Week Slide Ends, but CPI Decides Whether the Bounce Lasts”
WHAT HAPPENED. Gold snapped a two-week decline and gained roughly 1.6% on the week, then rose a further 0.3% on Monday, October 12 to about $4,206 its strongest level since October 2 as the dollar softened and oil slid off its morning high. The metal is still roughly 25% below its January record of about $5,608.
WHY IT HAPPENED — PRIMARY DRIVER (FED PRICING IS SETTLED, THE DATA IS NOT). After the weak September payrolls print covered in the prior edition, CME FedWatch now puts October hike odds at about 17%, down from 21.6% on October 7, but roughly 86% by December. That leaves the October 27–28 FOMC largely a hold, with the debate shifting to whether the Fed delivers a second hike this year. The 10-year Treasury yield is holding near 5.24% after topping 5.3% last week, and the dollar index sits around 102, so gold’s rebound has come without any relief from real yields.
SECONDARY DRIVER (GULF ESCALATION VS. A SURPRISE OIL DISCOUNT). Houthi militants struck Riyadh’s King Khalid International Airport on Saturday, killing 12 and injuring more than 300, and targeted it again on Sunday; President Trump is reportedly weighing joining Saudi Arabia in retaliating against the Houthis in Yemen. Yet Brent reversed lower after Trump announced an “energy ceasefire” between Russia and Ukraine Kyiv said the announcement was news to it, though it would honour a workable truce, and Moscow has not confirmed with more than 300,000 tonnes of Russian diesel expected to reach global markets. For gold, lower oil is helping because it eases the inflation-and-hike channel that has driven most of September’s selling.
SCENARIOS. Analysts flag the $4,000–4,050 zone as key support.
- Bull case: core CPI comes in cool, yields ease and gold extends toward $4,300.
- Bear case: a hot print revives hike pricing and pushes gold back toward the psychological $4,000 level.
- Main catalyst: Wednesday’s US CPI, where Reuters flags a headline reading near 3.7% balanced against a cooler core near 2.5%. Because headline and core point in opposite directions, the dollar’s reaction to the core figure will matter more than the headline.
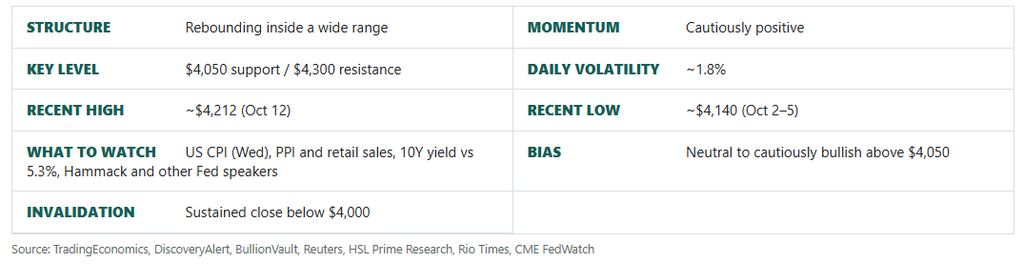
SILVER · ~$60.70–61.30/oz “Following Gold Up, but Not Keeping Pace”
WHAT HAPPENED. Silver traded near $60.70 into the weekend and rose about 0.5% to roughly $61.12 on Monday, a smaller gain than platinum (+1.0%) or palladium (+1.2%) on the day. At roughly 69:1, the gold-silver ratio is at the wide end of its recent range, meaning silver is still the laggard.
WHY IT HAPPENED. Silver is carrying the same rate-and-dollar headwind as gold with a higher beta: September’s slide from the high-$60s into the low-$60s has not been reversed, and a 5.2% ten-year yield keeps the opportunity cost of holding it elevated. Monday’s moves across gold, silver, platinum and palladium were broadly similar in direction, a sign that the move reflects currency and inflation expectations rather than silver-specific buying.
INDUSTRIAL DEMAND & PHYSICAL DEFICIT. The structural deficit thesis is unchanged and keeps a longer-run floor in place, but near-term price action is being set by rates.
- Bull case: a soft core CPI pulls yields lower and silver reclaims $64–67.
- Bear case: a hot print sends silver back toward the $57–58 shelf.
- Main catalyst: Wednesday’s CPI and the dollar’s reaction.
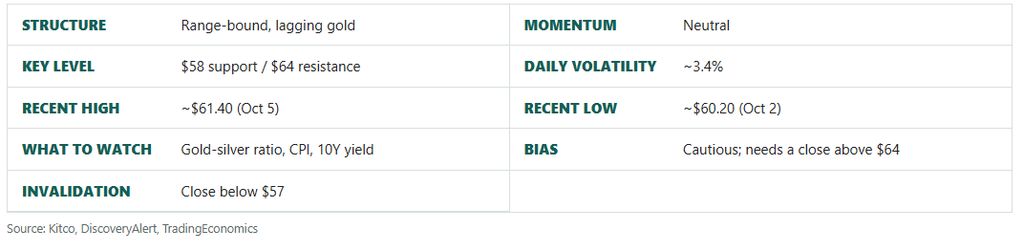
COPPER · ~$6.66–6.74/lb “Labour Risk Builds in Chile While the Price Holds Near $6.70”
WHAT HAPPENED. Copper rose 2.2% to $6.66/lb on Friday, October 9 up about 39% year-on-year and futures traded near $6.74 on Monday, with LME copper around $14,540 per tonne after a near-2% weekly gain. That keeps the metal below the September record above $14,875 but well above the lows seen earlier this month.
WHY IT HAPPENED — SUPPLY (PRIMARY DRIVER). The Escondida labour dispute is now the key variable. Supervisory workers at the world’s largest copper mine voted 95% to authorise a strike on October 1, and union members began a hunger strike on October 9 to pressure BHP back to the table. Chilean law requires mediation first, so a legal stoppage is still some steps away, but the mediation clock runs out this week. Separately, unions at Antofagasta’s Centinela project began industrial action, warning of production effects within about two weeks, though the company kept its output guidance. Analysts also note that spare metal is already stored in US warehouses, which has cushioned prices ahead of any actual walkout.
DEMAND (SECONDARY DRIVER). Grid, AI data-center and defense demand remain the structural support, though a 5.2% ten-year yield and oil above $100 keep a growth risk on the table.
- Bull case: mediation fails and strike action begins, pushing copper through its September record.
- Bear case: a wage deal is reached and the stockpile cushion releases metal back to market, sending copper toward $6.40–6.50.
- Main catalyst: the Escondida mediation outcome and the US refined-copper tariff decision, still unscheduled.
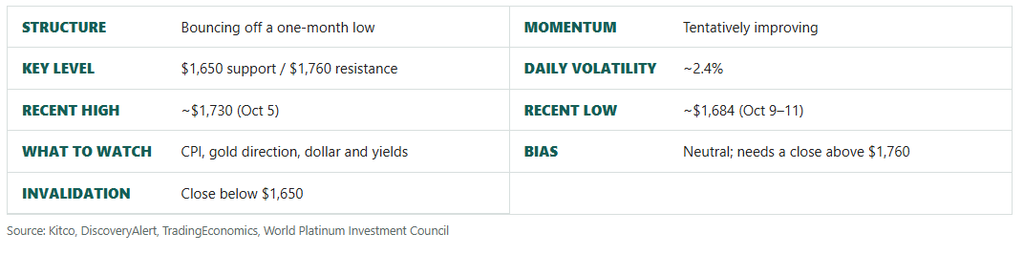
PLATINUM · ~$1,685–1,705/oz “A Modest Bounce From the Low-$1,680s, Still Soft on the Month”
WHAT HAPPENED. Platinum traded around $1,684–1,694 into the weekend and rose about 1.0% to roughly $1,705 on Monday, edging back toward the prior week’s levels. It remains about 6% lower than a month ago, even though it is still above year-ago levels.
SUPPLY & DEMAND BALANCE. The fundamental picture is unchanged: the WPIC projects a 265,000-ounce surplus in 2026, with automotive demand down 4% and industrial demand up 5%. Without a deficit narrative to cushion it, platinum is moving with the same rates, dollar and oil signals as gold and silver, which explains its similar day-to-day direction.
SCENARIOS.
- Bull case: a soft CPI pulls yields down and platinum retakes $1,760.
- Bear case: a hot print or a firmer dollar sends it toward $1,650.
- Main catalyst: Wednesday’s CPI and gold’s reaction to it.
This report is for informational purposes only and does not constitute investment advice. All prices are approximate and subject to market conditions. · Pan Asia Market Intelligence · 12 October 2026